You can scan a QR code and buy momos in Kathmandu using apps built for Mumbai streets. It feels like magic. People talk about cross-border payment links as if the job is completely done.
It is not.
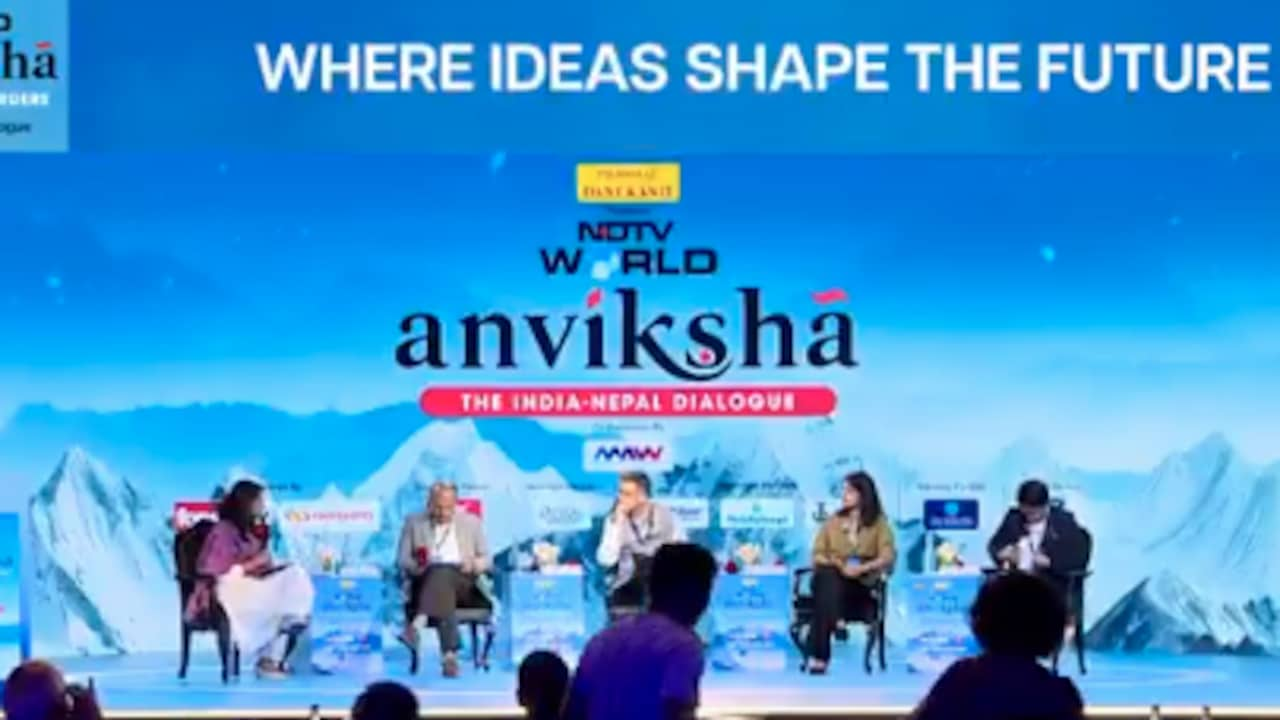
Getting money across the border is just the opening act. Real financial architecture requires identity checks, business-to-business pathways, and legal frameworks that actually speak to each other. During recent discussions at the NDTV Anviksha dialogue in Kathmandu, industry specialists laid bare what happens when you scratch beneath the shiny surface of retail QR codes.
Most everyday users assume that money movement equals total economic integration. That mistake costs businesses millions every single year.
The Identity Gap Nobody Talks About
Money moves fast. Paperwork crawls. That is the core friction holding back true India Nepal digital payment integration.
Dr Bal Krishna Bal from Kathmandu University pointed out a glaring reality during the panel sessions. Sending cash or retail funds across borders is only a fraction of the transaction lifecycle. You still hit walls when trying to verify who is actually sending or receiving that money.
Without unified identity verification and cross-border document exchange, the system lacks a complete loop.
Imagine trying to open a vendor account or clear compliance hurdles when your digital signature stops working the second it crosses a mountain range. It creates administrative gridlock. Payments work fine, but onboarding new partners takes weeks instead of seconds.
Why B2B Transactions Remain Stuck in the Past
If you are buying a cup of tea or paying for a hotel room, current retail payment rails like UPI and NPI handle things nicely. Switch lenses to enterprise trade, and the engine stalls entirely.
Surakchya Adhikari from Thulo.com highlighted a frustrating truth for regional e-commerce ventures. Retail transactions enjoy modern convenience, but business-to-business payments remain buried in legacy banking bureaucracy.
Try running global digital marketing campaigns or paying platform fees to major tech companies from a local startup account. You will immediately run into strict capital controls, multi-step approvals, and heavy fees. Young entrepreneurs watch global peers build tech empires instantly, only to hit physical and regulatory speedbumps on home soil.
Frustration builds quickly. The talent pool possesses immense drive, yet administrative drag holds them back.
Multi-Jurisdictional Legal Headaches
When cross-border digital rails fail or transactions get stuck in limbo, who fixes it?
Semanta Dahal, a legal expert at Abhinawa Law Chambers, noted that multiple institutional layers complicate dispute resolution. When a transaction breaks down across two sovereign banking systems, courts and regulators find themselves pointing fingers across borders.
Solving this requires direct regulator-to-regulator agreements. Without formal legal treaties designed specifically for multi-institutional electronic disputes, banks remain overly cautious. They freeze funds out of an abundance of caution, punishing legitimate merchants.
Until legal frameworks catch up with software speeds, cross-border commerce carries hidden risk.
What Smart Businesses Are Doing Right Now
You cannot wait for governments to harmonize every single policy before scaling your cross-border operations. If you operate in this corridor, you have to navigate the friction proactively.
- Diversify banking channels: Never rely on a single gateway for regional trade. Maintain relationships with traditional correspondent banks alongside newer fintech rails.
- Build compliance-first profiles: Keep corporate KYC documents notarized and ready in both jurisdictions to speed up manual overrides when automated systems stall.
- Factor in regulatory lag: Price the extra processing time and manual intervention costs directly into your financial forecasts.
The ambition is real. The software works. Now the legal and identity layers need to catch up.